
Fiat-to-Crypto Payment Gateways: How They Work and What the Rules Say
What a fiat-to-crypto payment gateway does, how it differs from crypto checkout and stablecoin settlement, and the Visa, Stripe, MiCA and FinCEN rules.

Article summary
TL;DR
A fiat-to-crypto payment gateway, or on-ramp, lets a customer pay with a card or bank transfer and receive crypto. Visa calls the provider a Ramp Provider: crypto purchases run on MCC 6051 or 6012 with Special Condition Code 7, a registered high-risk category. It is a different product from a crypto checkout, where the customer pays in crypto.
- Three products share the name: on-ramps (card in, crypto out), crypto checkouts (crypto in, fiat or stablecoins out) and stablecoin settlement between businesses.
- Visa puts crypto exchanges, wallets and on-ramps on MCC 6051 or 6012 with Special Condition Code 7, in Tier 2 of its Integrity Risk Program.
- Routing a sale through a ramp provider doesn't change its MCC: when a cardholder pays for goods, Visa wants the MCC of the business that sells them.
- In the EU, a crypto-asset service provider needs a MiCA authorization; the transition period ended on July 1, 2026 at the latest. In the US, FinCEN treats crypto payment processors as money transmitters.
- The card leg can still be disputed. Stripe, for example, says it takes on fraud and dispute liability on its own on-ramp.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
"Fiat to crypto payment gateway" covers three different products, and the card networks treat them very differently. This guide separates them, then walks through what Visa, Stripe, EU and US regulators actually require, and the questions to ask a provider before you sign.
What is a fiat-to-crypto payment gateway?
A fiat-to-crypto payment gateway takes a payment in ordinary money and delivers crypto in exchange. The customer pays by card, Apple Pay or bank transfer; the provider checks who they are, prices the coins and sends them to a wallet. The industry calls it an on-ramp. The reverse, crypto in and fiat out, is an off-ramp.
Visa has its own word for the provider.
An entity is a Ramp Provider if it provides payment services to convert transactions from a fiat currency to a non-fiat currency (for example: cryptocurrency), or vice versa.
A Ramp Provider can sell crypto to cardholders directly, or work for "Conversion Affiliates": wallets, apps and marketplaces that embed its widget.1Visa, Merchant Data Standards Manual, April 2026 That second model is what most "fiat to crypto payment processor" pages sell.
Fig. 1An on-ramp purchase
approved declined or closed routing step
- CustomerPays by card or bank transfer
- paysRamp providerKYC, sanctions screening, price quote
- authorizes onCard networkMCC 6051 or 6012, condition code 7
- sends toCrypto walletCoins delivered on-chainApproved
the card leg is a normal card payment
Fiat-to-crypto gateway, crypto payment gateway, stablecoin settlement
Search results mix three products. The difference is which way the money moves, and it decides which rules apply.
| Fiat-to-crypto gateway (on-ramp) | Crypto payment gateway | Stablecoin settlement | |
|---|---|---|---|
| Customer pays with | Card or bank transfer | Crypto from a wallet | Stablecoins (often business to business) |
| Who receives what | Customer receives crypto | Store receives fiat or stablecoins | Business receives fiat or stablecoins |
| What is being sold | Crypto itself | Your goods or services | Goods, services or a transfer |
| Card network MCC | 6051 or 6012, condition code 7 | NoCard leg | NoCard leg |
| Examples (from their own pages) | Stripe onramp, MoonPay | BitPay, Stripe stablecoin payments | Coinbase Payment Acceptance |
Verdict
If your customer ends up holding crypto, you are looking at an on-ramp and the card rules on crypto apply. If your customer pays you in crypto for a product, it's a crypto payment gateway: no card in the flow, so none of the crypto MCC rules, but also none of the card protections.
For an online store selling physical goods, the second column is usually the relevant one: an extra payment method next to cards, like other alternative payment methods. The first column is for businesses that sell crypto.
How Visa classifies a fiat to crypto payment processor
Visa's April 2026 MCC manual sets three rules for anyone selling crypto against a card.1Visa, Merchant Data Standards Manual, April 2026
Crypto purchases are quasi-cash
Any non-fiat acquisition is flagged
Acquisitions of non-fiat currency must use MCC 4829, 6012, 6051 or 6540 as applicable, with the special condition indicator in both the authorization and the clearing record.
The ramp provider assesses each affiliate
A Ramp Provider is a third party. It must evaluate the business of every Conversion Affiliate and assign the MCC that fits that business.
Visa's examples make it concrete. A cardholder who buys Bitcoin from a ramp provider and sends it to their own wallet: MCC 6051, because the provider isn't a financial institution. A bank selling a tokenized bond to its cardholder: MCC 6012.1Visa, Merchant Data Standards Manual, April 2026
Tier 2 of the Integrity Risk Program
On top of the coding, Visa lists "6051 and 6012 Crypto Merchants: exchanges, wallet providers or on-ramp providers (card absent)" among its high-risk merchants.1Visa, Merchant Data Standards Manual, April 2026 In the Visa Integrity Risk Program, crypto sits in Tier 2, the "risk of financial harm" tier, alongside cyberlockers and skill games with wagering.2Visa, Visa Integrity Risk Program guide for acquirers, April 6, 2023
- The acquirer gets a Tier 2 approval from Visa. One approval covers all Tier 2 categories, with an initial control assessment and a yearly self-assessment.
- The acquirer runs enhanced due diligence on the merchant. It checks the business, its controls and its licenses.
- The acquirer registers the merchant with Visa. Registration comes before the first card-absent transaction.
Source: Visa Integrity Risk Program guide for acquirers. The full list of codes and tiers is in our guide to high-risk MCC codes.
Not every acquirer holds that approval, so an on-ramp has fewer banks to choose from. More on how tiers work in high-risk MCC codes.
Why crypto rails don't change your MCC
The old pitch for "fiat-to-crypto routing" in ecommerce was that it moves a hard-to-process sale onto crypto rails and away from your category. Visa's manual closes that door explicitly.
If the cardholder is paying a Ramp Provider's Affiliate for goods/services, the MCC should be the MCC appropriate for the type of item purchased or the Affiliate's primary business as per Visa's regular MCC assignment rules, when permitted. Also, if the transaction is on behalf of another High-Risk Merchant, then the MCC of that merchant must be used.
Visa's own example: a cardholder buys Ethereum through a ramp provider in order to gamble with an affiliate. The transaction must carry MCC 7995, gambling, not 6051.1Visa, Merchant Data Standards Manual, April 2026 The card payment is coded for what the customer is really buying.
Changing the data to get through is a rule breach
Visa's Core Rules forbid changing authorization data, including the MCC, when a payment is retried after a decline. Changing a merchant's name, data or performance to get around Visa's monitoring programs can cost the acquirer up to USD 25,000 per merchant per month, and the merchant and its owners can be excluded.3Visa Core Rules and Visa Product and Service Rules, April 18, 2026
So for a store with approval problems, a crypto layer doesn't replace a correct MCC and a processor that accepts the business. That part is covered in high-risk ecommerce payment resilience.
What Stripe allows for crypto businesses
Processors add their own rules on top of Visa's. Here is what Stripe's list said for crypto-related businesses on October 14, 2026.4Stripe, Prohibited and restricted businesses (read October 14, 2026)
| Business | At Stripe |
|---|---|
| Crypto exchanges and crypto wallets | RestrictedNeeds approval |
| Cryptocurrency (other uses) | RestrictedLimited: contact Stripe's sales team |
| Money transmission and other money services | RestrictedNeeds approval |
| Crypto mining and crypto deposits | Prohibited |
| Initial coin offerings (ICOs) | Prohibited |
| Peer-to-peer money transmission | Prohibited |
Stripe also runs its own crypto products, described below. Using them is a separate application from getting your crypto business accepted on a standard Stripe account.
Inside Tagada
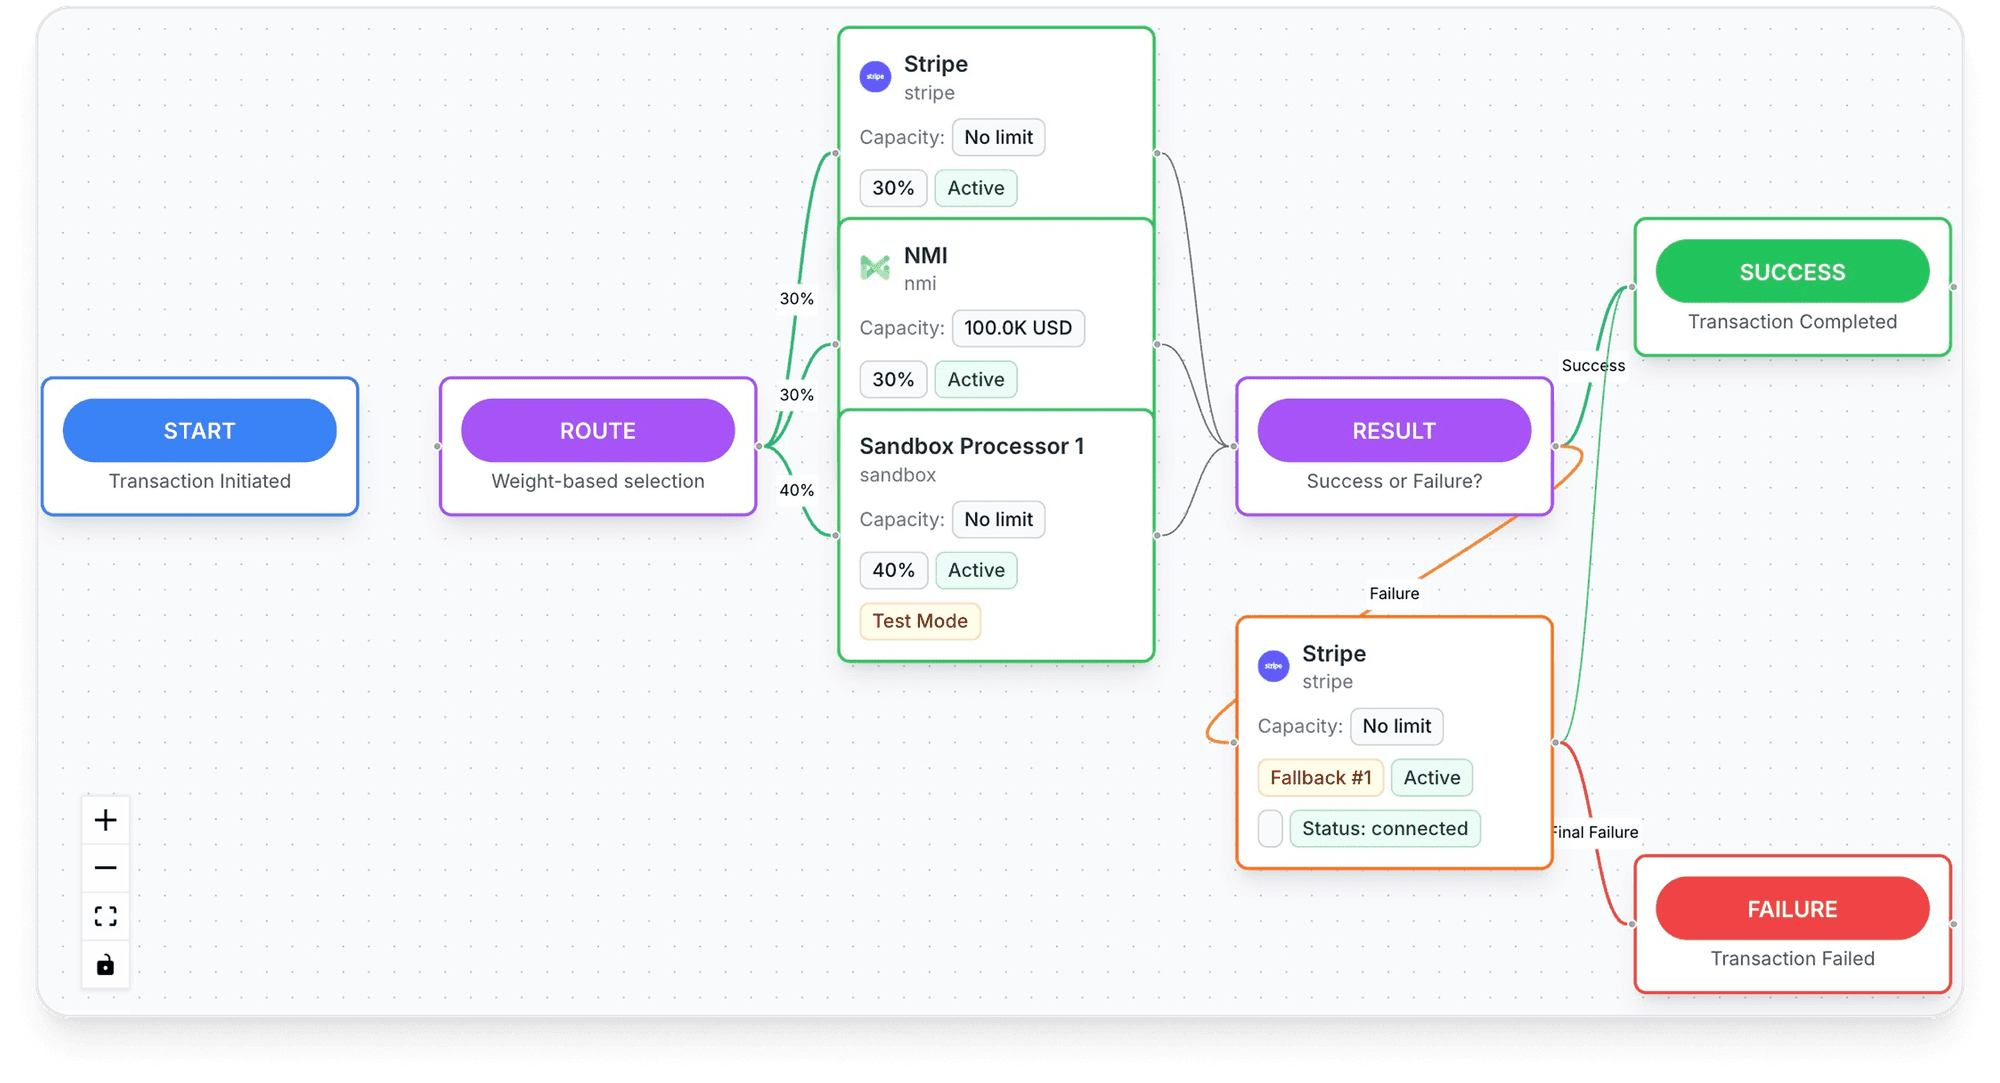
See every payment's route, processor by processor
Set the order your processors are tried in, per store, per country or per product.
Regulation: MiCA in the EU, FinCEN in the US
Whoever converts fiat into crypto is regulated as a financial service. The two texts below are the primary sources most providers cite.
EU: Regulation (EU) 2023/1114 (MiCA)
MiCA lists "exchange of crypto-assets for funds" and "exchange of crypto-assets for other crypto-assets" among crypto-asset services. Under Article 59, no one may provide those services in the EU unless authorized as a crypto-asset service provider (CASP), or already licensed as a bank, e-money institution, investment firm or similar entity allowed to offer them.7Regulation (EU) 2023/1114 on markets in crypto-assets (MiCA), May 31, 2023
Fig. 2MiCA dates for crypto service providers
- June 30, 2024Rules on stablecoin issuers (Titles III and IV) apply
- Dec 30, 2024MiCA applies in full, including to service providers
- July 1, 2026Latest end of the transitional period for providers already active under national law
the grace period is over
MiCA also sets who may offer a euro or dollar stablecoin to the public. It calls them e-money tokens, crypto-assets that "purport to maintain a stable value by referencing the value of one official currency", and only an authorized credit institution or e-money institution may issue them.7Regulation (EU) 2023/1114 on markets in crypto-assets (MiCA), May 31, 2023
US: FinCEN guidance FIN-2019-G001
FinCEN's May 2019 guidance applies the money transmitter rules to crypto business models.8FinCEN, FIN-2019-G001, Application of FinCEN's Regulations to Certain Business Models Involving Convertible Virtual Currencies, May 9, 2019
- Exchangers are money transmitters. A business that exchanges virtual currency for real currency, funds or other virtual currency generally is one, with the money services business obligations that come with it.
- Crypto payment processors are money transmitters too. FinCEN says they don't qualify for the payment processor exemption, because they don't settle only through systems limited to BSA-regulated financial institutions.
- Users are not. A person who obtains virtual currency to buy goods or services on their own behalf isn't a money transmitter.
Licensing doesn't stop at FinCEN: MoonPay, for example, lists money transmitter licenses in 47 US states and a New York BitLicense on its business page.9MoonPay, Onramp for business (read October 14, 2026) See the glossary entries on FinCEN and the money transmitter license.
What this means for a store
A merchant that accepts crypto for its goods through a licensed processor is in the "user" position in FinCEN's framework. A merchant that starts selling crypto to its customers, or holding and transferring it for them, is in a different one. Ask a lawyer before you cross that line.
Stablecoin-to-fiat payments for businesses
The third product is the one corporate treasurers search for: getting paid in a stablecoin and receiving fiat currency. Here is what three providers say on their own pages, read on October 14, 2026.
What the providers state
- Stripe stablecoin payments: customers pay in USDC (on Tempo, Ethereum, Solana, Polygon and Base) and other supported tokens; payments settle in your Stripe balance in your local currency; open to US businesses, in private preview in the EU, Hong Kong, Mexico and Switzerland.
- Coinbase Payment Acceptance: for payment providers, marketplaces and large platforms; buyers pay in USDC or USDT; settlement in USD or USDC.
- BitPay: settlement "in fiat direct to your bank account, crypto, or a mix of both."
Limits they also state
- Stripe: refunds always go back as stablecoins to the customer's original wallet; 10,000 USD per transaction; no dispute support.
- Coinbase: access requires onboarding with its team, with enhanced due diligence.
- BitPay: "Blockchain payments are irreversible."
Sources: Stripe Docs, Coinbase Developer Platform, BitPay.6Stripe Docs, Stablecoin payments (read October 14, 2026)10Coinbase Developer Platform, Payment Acceptance overview (read October 14, 2026)11BitPay, Crypto payments for business (read October 14, 2026) Fees aren't listed on these pages; ask for a written quote.
How to evaluate a fiat-to-crypto provider
Provider pages answer the same questions in different places. Start with these.
| Question | What to look for | Example from a provider's own page |
|---|---|---|
| Who is the merchant of record? | The provider, or you | Stripe acts as merchant of record for onramp transactions |
| Who carries fraud and dispute losses on the card leg? | Written in the contract | Stripe "assumes full liability for all fraud and disputes" on its onramp |
| Who runs KYC and sanctions screening? | The provider, before delivery | MoonPay: "Fraud checks, chargebacks, KYC, sanctions screening — all done by MoonPay" |
| Which licenses, where? | MiCA authorization in the EU, state licenses in the US | MoonPay lists MiCA authorization, a New York BitLicense and licenses in 47 states |
| How do you get access? | Application, review, sandbox | Stripe: onramp application first, most reviewed within 48 hours |
| What do you receive, and how is it refunded? | Fiat, stablecoins, or both | Stripe stablecoin payments: local currency in, stablecoin refunds out |
Sources: Stripe Docs; MoonPay.5Stripe Docs, Stripe fiat-to-crypto onramp (read October 14, 2026)9MoonPay, Onramp for business (read October 14, 2026)6Stripe Docs, Stablecoin payments (read October 14, 2026) If a provider can't show you its license numbers and its merchant of record terms, you have your answer.
Risks: volatility, chargebacks and fraud
- Price movesCrypto prices change between quote and delivery; stablecoins only purport to hold their peg, in MiCA's wordsWho bears the gap between quote and settlement, and how fast you convert to fiat
- Chargebacks on the card legPaying by card for crypto is a normal card payment, with the cardholder's dispute rightsWho is liable in the contract: Stripe takes it on for its onramp; others may not
- Stolen cardsCrypto leaves fast and can't be pulled back, which makes on-ramps a target for stolen cardsKYC before delivery, 3-D Secure, limits for new users
- No dispute, no recourseA crypto payment can't be reversed by a bank, for you or for the customerA clear refund policy, since refunds are your only tool
- Licensing gapsA provider without the right license can be forced to stop serving a marketCheck the license register in each market you serve
The "no chargebacks" line on crypto pages only covers the crypto leg. Any part of the flow that runs on a card keeps the card rules, and your chargeback exposure moves to whoever is merchant of record for that card payment.
Does it make sense for an ecommerce brand?
| Your situation | Fit |
|---|---|
| You sell crypto, or a wallet or app where users buy it | FitsOn-ramp, through a licensed provider |
| You sell goods and some customers ask to pay in crypto | FitsA crypto payment gateway as one more method |
| You get paid by business clients who hold stablecoins | FitsStablecoin settlement |
| You want to move card sales off your MCC through crypto rails | Does not fitVisa codes the sale for what is bought |
| You want to escape chargebacks on card payments | Does not fitThe card leg keeps its dispute rights |
How Tagada helps
Where Tagada fits
Tagada works on the card side of the checkout. It routes payments across TagadaPay and processors such as Stripe, NMI and Airwallex, with one logic, and cascades to another processor when one is down or times out. Its card vault lets you switch processors without re-onboarding customers, so running subscriptions keep charging. 3D Secure 2 is native, with device intelligence and a rules engine. Each TagadaPay business is underwritten, with enhanced review on regulated verticals. Pricing is on the pricing page. Tagada follows Visa and Mastercard rules and the laws that apply to payments.
If your card approvals are the real problem, start with the basics: the right MCC, a processor that accepts your business, and a backup. The payment gateway vs payment processor guide explains who decides what in a card payment.
Frequently asked questions
What is a fiat to crypto payment gateway?
What is the difference between a fiat-to-crypto gateway and a crypto payment gateway?
Which MCC does a crypto on-ramp use?
Can crypto payments be charged back?
What is stablecoin-to-fiat settlement for businesses?
What is a crypto-to-fiat off-ramp?
Sources
Checked October 14, 2026- Visa, Merchant Data Standards Manual, April 2026
- Visa, Visa Integrity Risk Program guide for acquirers, April 6, 2023
- Visa Core Rules and Visa Product and Service Rules, April 18, 2026
- Stripe, Prohibited and restricted businesses (read October 14, 2026)
- Stripe Docs, Stripe fiat-to-crypto onramp (read October 14, 2026)
- Stripe Docs, Stablecoin payments (read October 14, 2026)
- Regulation (EU) 2023/1114 on markets in crypto-assets (MiCA), May 31, 2023
- FinCEN, FIN-2019-G001, Application of FinCEN's Regulations to Certain Business Models Involving Convertible Virtual Currencies, May 9, 2019
- MoonPay, Onramp for business (read October 14, 2026)
- Coinbase Developer Platform, Payment Acceptance overview (read October 14, 2026)
- BitPay, Crypto payments for business (read October 14, 2026)
TagadaPay
Selling goods, not crypto? Keep your card side resilient
Tell us what you sell and how you sell it. Each application is underwritten, and approval is not guaranteed.
- 01Tell us what you sell and how
- 02Underwriting reviews your business
- 03Process through TagadaPay alongside your other processors